

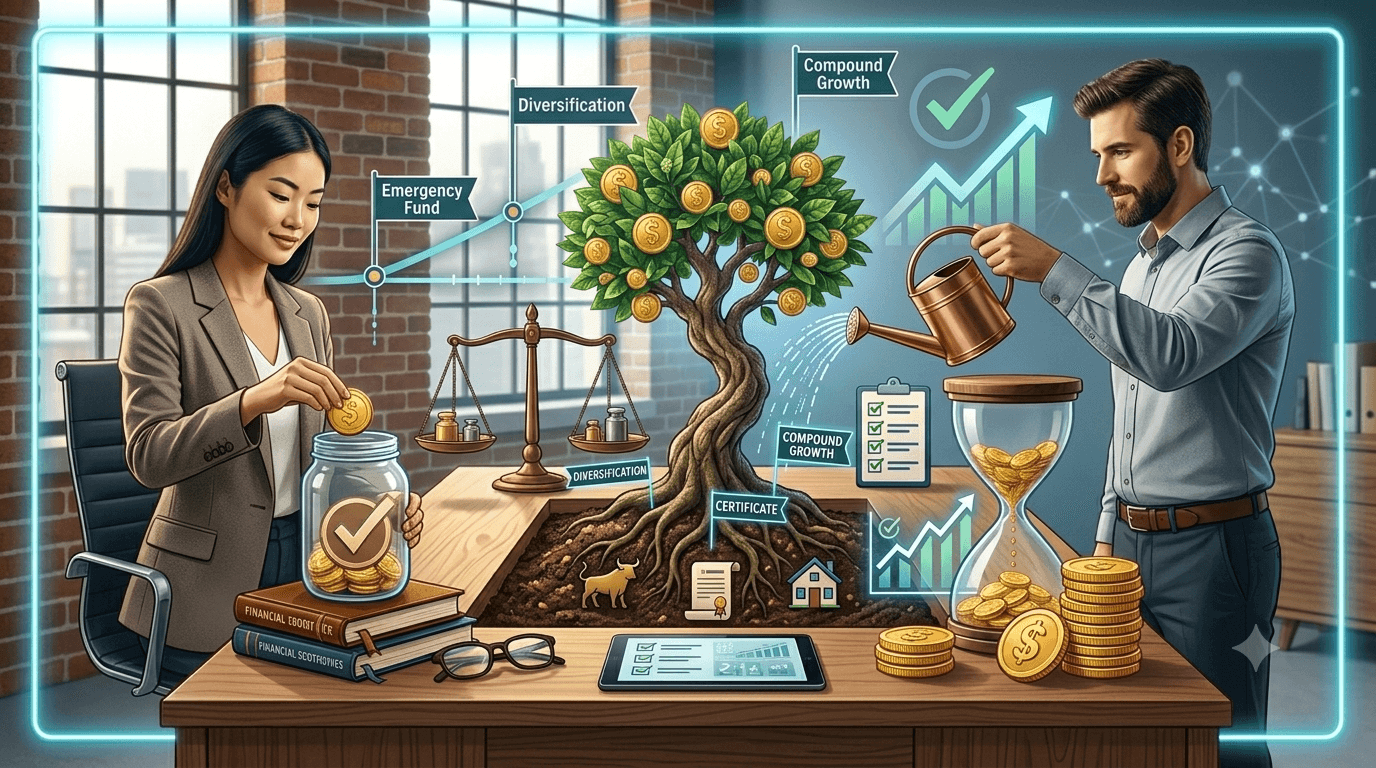
Leaving your hard-earned money idling in a standard savings account is a guaranteed way to lose purchasing power over time. With macroeconomic pressures altering the value of liquid cash, individual financial security requires moving from a mindset of passive saving to active investing. For beginners, navigating the local investment landscape can feel intimidating due to jargon and fear of market volatility. However, by breaking down local asset classes based on risk, return, and accessibility, any salaried professional or freelancer can build a resilient wealth-generating portfolio.
Local Investment Spectrum (Risk vs. Return)
1. Savings Certificates (Sanchayapatra)
Risk Level: Low
Potential Return: Low to Moderate
Characteristics: Fixed returns, government-backed, suitable for conservative investors seeking stability and predictable income.
2. Mutual Funds (Managed & Diversified)
Risk Level: Medium
Potential Return: Moderate
Characteristics: Professionally managed portfolios, diversified investments, balanced growth potential with controlled risk.
3. Direct Stocks
Risk Level: High
Potential Return: High
Characteristics: Direct ownership in companies, higher volatility, requires active monitoring and long-term investment discipline.
The Bedrock of Low-Risk Stability: Savings Certificates (Sanchayapatra)
For absolute beginners or those with a low tolerance for risk, National Savings Certificates (known locally as Sanchayapatra) remain an incredibly reliable vehicle. Backed directly by the government, these instruments offer fixed, predictable returns that are typically higher than standard bank fixed deposits (FDRs).
How They Work: You buy these certificates through the central bank, commercial banks, or national post offices for fixed tenures (usually 3 to 5 years).
The Strategy: While the government has introduced investment caps and multi-tiered interest rates to regulate them, they remain an exceptional choice for emergency funds or retirement baskets because the principal amount is completely secure. The profit is distributed quarterly or upon maturity, offering steady cash flow.
The Middle Ground: Mutual Funds
If you want your savings to outpace inflation but lack the time or expertise to analyze corporate financial statements, mutual funds offer an ideal compromise. A mutual fund pools money from thousands of individual investors to purchase a diversified portfolio of stocks, bonds, and corporate debt instruments.
Professional Management: These funds are managed by licensed Asset Management Companies (AMCs) and professional fund managers.
Asset Types: Beginners should focus primarily on Open-Ended Mutual Funds. Unlike closed-ended funds traded on the stock exchange, open-ended funds allow you to buy or sell fractional units at any time based on the current Net Asset Value (NAV).
The Approach: Many local AMCs now offer Systematic Investment Plans (SIPs). An SIP allows you to invest a fixed amount (as low as 1,000 to 5,000 BDT) every single month. This automates your investments and averages out your purchase costs over time, shielding you from sudden market dips.
High-Growth Potential: Navigating the Stock Market
The stock market represents ownership in real companies. Investing through the Dhaka Stock Exchange (DSE) offers the highest potential long-term returns, but it comes with a matching level of risk. To start, you must open a Beneficiary Owner (BO) account through a licensed stockbroker. As a beginner, you must strictly avoid speculative day trading or acting on casual "market tips." Instead, focus your capital on Blue-Chip Stocks—shares of long-standing, well-governed companies with stable balance sheets, clear corporate governance, and a history of paying regular dividends (such as leading multinationals, established pharmaceuticals, and top-tier commercial banks). Think of the stock market as a 5-to-10-year holding commitment, allowing compound interest to work its magic.
Comments
0